The lowest monthly payment can end up costing more over time. When a heating or cooling repair or replacement strains your budget, it’s understandable to focus on what you’ll owe each month. But comparing HVAC financing options also means looking at the APR, the total repayment amount, and what happens when a promotional period ends.
This guide explains common ways to pay for HVAC work and the tradeoffs to consider, whether you’re facing a repair or planning a system replacement. You’ll learn how to compare financing terms beyond the monthly payment, understand details such as deferred interest, and identify what to gather before reviewing payment choices. A clear project scope and quote can help you weigh the cost against your budget and make a considered decision without feeling rushed into work you don’t need.
Key Takeaways
- Financing can spread payments for HVAC work, but it doesn’t mean replacement is always better than repair.
- Compare HVAC financing options by APR, total repayment, flexibility, and offer conditions, not just the monthly payment.
- Understand how cash, credit cards, personal loans, and project financing differ before choosing a payment method.
- Clarify the work needed and separate essential repairs or replacements from optional upgrades before reviewing payment terms.
- A project-specific quote helps you understand the work and assess whether the payment plan fits your budget.
When HVAC Financing Options May Help With a Repair or Replacement
HVAC financing spreads the cost of heating or cooling work over time under agreed payment terms. It may help when paying the full amount at once doesn’t fit your budget, but financing is a way to manage a project, not a reason to replace a system that can be repaired. Start by understanding the equipment’s condition and the recommended work. Then consider how the payment terms fit your finances.
The decision can look different for a planned replacement than for an unexpected repair. If a furnace, air conditioner, or boiler is nearing the end of its useful life, you may have time to review a replacement scope and compare payment choices. A repair may arise with less warning, so first understand the recommended work and its cost. In either case, the project scope and financing terms affect which choices fit. Peters Heating & Cooling offers financing options, with terms and eligibility determined by the financing arrangement.
Which HVAC projects might lead homeowners to consider financing?
A furnace repair, air conditioner replacement, or boiler installation can each involve a different scope of work. A written project description helps show what the work includes. For an installation, the quote can account for equipment, labor, and necessary permits, giving you a clearer basis for understanding how much you may need to finance. Don’t assume every repair or installation has the same terms. For a larger planned project, some homeowners also explore a Home Equity Loan, a form of borrowing against home equity. Financing is a payment tool, not a reason to add optional work or replace equipment that can be repaired.
How can a business think about HVAC financing?
For a light-commercial space, heating and cooling work can affect employee or customer comfort and normal operations. A business may need to plan project payments alongside payroll, inventory, and other operating expenses, which differs from balancing a household budget. A clear scope helps a business assess the work and its effect on cash flow without assuming residential and commercial projects have identical needs. Learn more about light-commercial HVAC services for local businesses.
Common HVAC Financing Options and How They Work
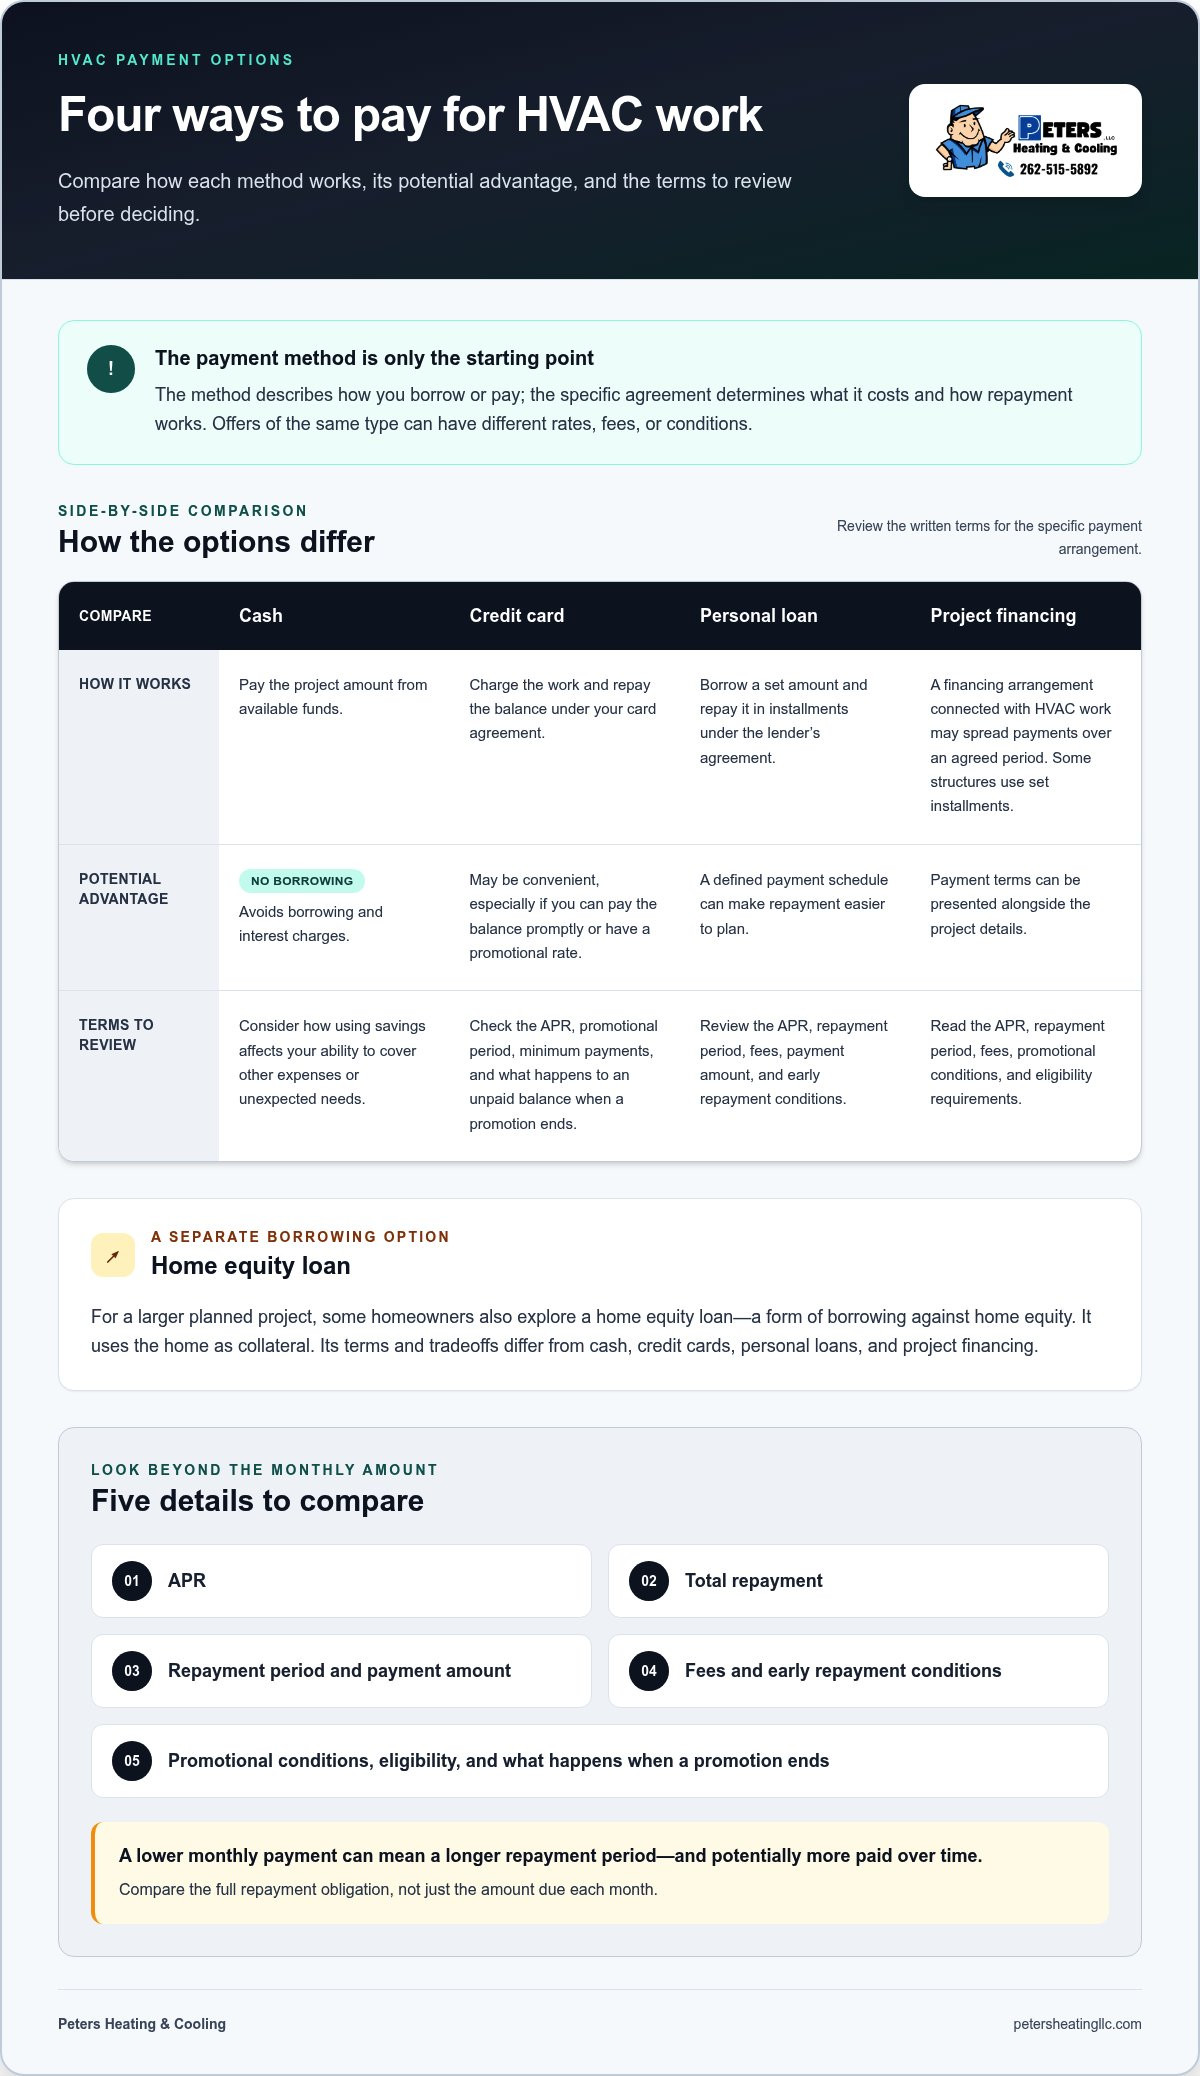
There’s more than one way to pay for heating or cooling work. The right fit depends on the project, your available funds, and the terms you qualify for. Use this comparison as a starting point, then review the agreement to understand what you’ll pay.
| Payment method | How payments work | Potential advantage | Terms to review |
|---|---|---|---|
| Cash | Pay the project amount from available funds. | Avoids borrowing and interest charges. | Consider how using savings affects your ability to cover other expenses or unexpected needs. |
| Credit card | Charge the work and repay the balance under your card agreement. | May be convenient, especially if you can pay the balance promptly or have a promotional rate. | Check the APR, promotional period, minimum payments, and what happens to any unpaid balance when a promotion ends. |
| Personal loan | Borrow a set amount and repay it in installments under the lender’s agreement. | A defined payment schedule can make repayment easier to plan. | Review the APR, repayment period, fees, payment amount, and early repayment conditions. |
| Project financing | A financing arrangement connected with HVAC work may spread payments over an agreed period. Some structures use set installment payments. | It can put payment terms alongside the project details. | Read the APR, repayment period, fees, promotional conditions, and eligibility requirements. |
A financing method describes how you borrow; the specific terms determine what it costs and how you repay. Two offers using the same type of loan can have different rates, fees, or conditions. Review the written terms for the specific financing arrangement.
What should you know about HVAC project financing?
Peters Heating & Cooling offers financing options to customers. A fixed-payment structure generally means repaying a borrowed amount through scheduled payments, but the repayment period and cost depend on the agreement. Review the APR, repayment period, fees, and any promotional conditions before comparing offers. Don’t judge an offer by its monthly payment alone; consider the full repayment obligation, too.
How do credit cards, personal loans, and cash compare?
Cash avoids borrowing, but using savings can leave less available for other needs. Credit card and personal loan costs depend on the account or lender agreement. A home equity loan is another borrowing method, but it uses the home as collateral, as explained by the Consumer Financial Protection Bureau. Each approach has different tradeoffs, so none is automatically the cheapest or best for every project.
For a clearer starting point, review Peters Heating & Cooling’s heating and cooling services alongside the project scope you’re considering.
How to Compare HVAC Financing Offers Beyond the Monthly Payment
A manageable payment can make a project easier to plan, but it doesn’t show the full cost of borrowing. Compare each offer across several factors, then read the written terms to understand what could change the amount or timing of payments.
| Factor | Potential advantage | Tradeoff or condition to review |
|---|---|---|
| Monthly payment | A predictable amount can make it easier to plan household expenses. | A lower monthly payment can mean a longer repayment period and potentially more paid over time. |
| Total repayment | Comparing the full amount due helps show the overall cost of borrowing. | The total can depend on interest, fees, and whether promotional terms apply. |
| Flexibility | Some agreements may allow early repayment or offer a set payment schedule. | Rules for extra payments, early payoff, or changing payment dates vary by agreement. |
| Conditions | A promotional period may offer a lower borrowing cost while it lasts. | Eligibility, deadlines, and what happens when the promotion ends can affect the final cost. |
Which financing terms deserve careful attention?
APR, or annual percentage rate, expresses borrowing costs as an annualized rate. It helps compare costs, while the monthly payment tells you the scheduled amount due. Neither figure tells the whole story alone. Check the repayment length, fees, late-payment terms, and any promotional period. If an offer mentions deferred interest, the agreement should explain how interest is handled and what happens if the balance isn’t paid by the stated deadline. Keep the written disclosures and review them before accepting. For broader context on loan comparisons, see Forbes Advisor’s home improvement loan guide.
How can you compare an offer with your budget?
Set the regular payment beside the total repayment amount and your essential monthly expenses. Consider whether the payment would still fit if an unexpected cost came up or your income changed. This is a practical way to judge how much room your budget has. Compare the same details across offers, and don’t rely on a promotional payment that may not continue for the full repayment period.
HVAC financing options are easier to assess when the project scope and written terms are clear. Comparing them carefully helps you weigh predictable payments against total cost and conditions, without treating any one offer as the right fit for everyone.
A Practical Checklist Before Choosing HVAC Financing
Preparation makes financing choices easier to compare. Use this checklist to connect the work being considered with its cost and payment terms, whether you’re planning a household repair or managing a business project.
What project details should you understand first?
Start with the diagnosis and recommended work. Gather equipment details and an itemized quote so you can see what the project includes. A repair and a replacement are different scopes, so compare payment choices against the same proposed work. For a light-commercial example, read this light-commercial AC repair case study.
What should you review before agreeing to financing?
Read the complete written terms, including the payment schedule, APR, fees, and any promotional conditions. Consider the regular payment alongside essential household expenses or business commitments. Don’t sign until both the project scope and financing terms make sense to you.
- Define the HVAC issue. Understand what needs attention and the recommended solution before focusing on payment.
- Review the project scope. Look over the diagnosis, equipment details, and itemized quote. Separate necessary work from optional upgrades so you can decide what the project includes.
- Compare the same scope across payment choices. A repair quote and a replacement quote cover different work. Make sure the amounts you compare relate to the same project rather than judging one payment plan against a different scope.
- Read and retain the disclosures. Check the full repayment terms, including fees, payment timing, and what happens when a promotional period ends. Keep the documents for reference.
- Check the fit with your budget. Consider how the payment sits alongside regular expenses and whether your budget has room for unexpected costs or changes in income.
This process puts HVAC financing options in context: they’re a way to manage a considered project, not a reason to add work you don’t need. A clear scope and understandable written terms give you a steadier basis for deciding whether a payment plan fits.
Review your HVAC project with Peters Heating & Cooling.
Explore HVAC Financing Options With a Clear Project Plan
A sound payment decision starts with understanding the work. Review the recommended repair or installation, compare the written financing terms, and consider whether the payments fit your household or business budget. Financing can help spread payments, but it should support a project that makes sense for your heating and cooling needs.
A project-specific installation quote can make the decision clearer by outlining equipment, labor, and necessary permits. With the scope in hand, you can compare payment choices against the same work rather than relying on a monthly payment without context. Peters Heating & Cooling serves residential and light-commercial customers and offers financing options. Specific terms depend on the financing arrangement.
What happens when you discuss an HVAC project?
The conversation begins with the system issue and the work being considered. For a repair, that means understanding what needs attention; for an installation, a project quote details the equipment, labor, and necessary permits. Clear pricing and honest recommendations help you understand the work before considering how to pay. The goal is a useful picture of the project, not pressure to choose a particular payment method.
How can local customers take the next step?
Homeowners and small businesses in Kenosha, Racine, Oak Creek, and Winthrop Harbor are among the communities Peters Heating & Cooling serves across Southeast Wisconsin and Northeast Illinois. Light-commercial projects can have different operating needs from a household system. For related local business context, read about HVAC contractor expectations in Zion, Illinois.
Before deciding, make sure the project scope is clear, the written financing terms are understandable, and the payment fits your budget. Comparing those details can help you decide whether HVAC financing options suit the project, without treating financing as a reason to take on unnecessary work.
For a straightforward conversation about the work you’re considering, talk with Peters Heating & Cooling about your HVAC project.
Make Your Next HVAC Payment Decision With Confidence
A repair or replacement can put pressure on a household or business budget, but the payment decision doesn’t need to be rushed. Start by understanding the recommended work and reviewing a clear project scope. Then compare HVAC financing options by APR, total repayment, repayment period, and conditions, not just the monthly amount.
Cash, cards, personal loans, and project financing each have tradeoffs. The right fit depends on the written terms and how payments work with your other expenses. Financing is one possible way to manage a needed project, not a reason to replace equipment that can be repaired or add upgrades you don’t need.
Peters Heating & Cooling provides residential and light-commercial HVAC repair and installation, with financing options available. A clear quote helps you understand the work before weighing how to pay. With the details in hand, you can choose your next step with greater confidence and a clearer view of your budget.
Frequently Asked Questions
What are the most common HVAC financing options?
Common HVAC financing options include project financing, credit cards, and personal loans. Some homeowners also consider a home equity loan, while paying with cash avoids borrowing. Each method has different terms and tradeoffs. Compare APR, fees, repayment period, total repayment, and any promotional conditions rather than choosing by the monthly payment alone. Approval requirements and terms vary by financing arrangement.
Is HVAC financing available for repairs as well as replacements?
Peters Heating & Cooling offers financing options, and terms depend on the project and financing arrangement. A furnace repair, air conditioner repair, or boiler replacement can involve different scopes and costs, so don’t assume one set of terms applies equally to every job. A clear description of the recommended work helps you understand what you’re considering paying for.
Can I get HVAC financing with less-than-perfect credit?
Approval and terms depend on the lender’s eligibility requirements and your application. A lower credit score may affect whether you qualify or the APR and repayment terms offered, so no specific outcome can be assumed in advance. Review the complete written offer, including fees and total repayment, before agreeing. Compare the terms with your budget, and don’t rely on the monthly payment alone to judge affordability.
How much does HVAC financing cost?
The cost depends on the amount financed, APR, repayment period, fees, and any promotional conditions. To understand the full obligation, compare the total repayment amount as well as the scheduled payment. A lower monthly payment may reflect a longer repayment period, which can affect the amount paid overall. The project quote clarifies the work being financed, while the lender’s written disclosures explain borrowing costs and terms.
What happens if I miss an HVAC financing payment?
Consequences depend on the financing agreement. A missed payment may lead to late fees, additional interest, or other effects described in the lender’s terms. If the offer includes a promotional period, missed or late payments may also affect how its conditions apply. Read the written disclosures so you know the agreement’s rules. If you think a payment may be late, contact the lender promptly to understand the available steps.
Should I finance an HVAC repair or pay out of pocket?
Choose based on the repair scope, your available savings, and the full cost of financing. Paying out of pocket avoids borrowing, but consider whether it would leave enough savings for other household needs. Financing can spread payments, but interest and fees may increase the total cost. Compare the repair quote with the written payment terms, then decide what fits your budget. Peters Heating & Cooling serves customers in Kenosha, Racine, Oak Creek, and Winthrop Harbor.